Let \((X,\mcm,\mu)\) be a measure space, let \(f\colon X\to\CC\) be measurable, let \(\alpha>0\), and put \(S_\alpha\coloneqq\theset{x\in X\suchthat\abs{f(x)}>\alpha}\). Then \[ \mu(S_\alpha) \leq \frac{1}{\alpha}\int_X\abs{f}\dmu = \frac{1}{\alpha}\norm{f}_1, \] and more generally, for \(0<p<\infty\), \[ \mu(S_\alpha) \leq \frac{1}{\alpha^p}\int_X\abs{f}^p\dmu = \frac{1}{\alpha^p}\norm{f}_p^p. \]
On \(S_\alpha\) we have \(\abs{f(x)} > \alpha\), hence \(\abs{f(x)}^p > \alpha^p\), so \[ \int_X \abs{f}^p\dmu \geq \int_{S_\alpha} \abs{f}^p\dmu \geq \int_{S_\alpha} \alpha^p\dmu = \alpha^p \mu(S_\alpha). \] Dividing by \(\alpha^p > 0\) gives the second inequality, and \(p=1\) gives the first.
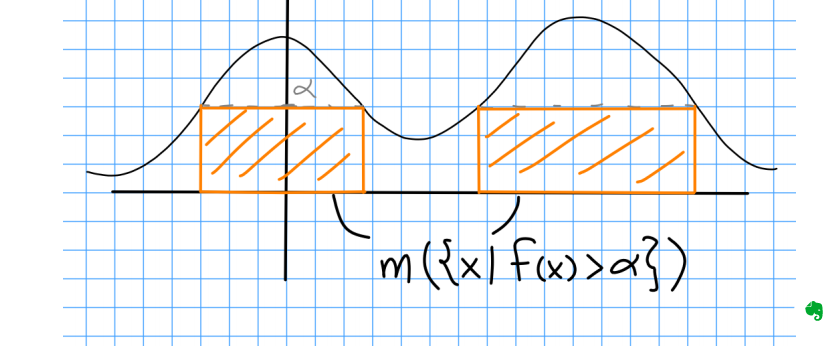
For a probability space \((\Omega,\mathcal F,P)\) and a nonnegative random variable \(Y\) with expectation \(E(Y)\), the case \(p=1\) reads \(P(Y>\alpha)\leq E(Y)/\alpha\).